Japan Markets ViewGlobal Security Experts (4417) in Spotlight for Cybersecurity Measures
Oct 08, 2026
[Akira Motoyoshi, QUICK Market Eyes] Market interest is growing in Global Security Experts (TSE Growth Market), whose core business is cybersecurity measures. This comes as the cost of cyberattacks drops dramatically due to the misuse of generative artificial intelligence (AI) and AI agents. Consequently, automated attacks are causing a series of personal information leaks and system failures in Japan.
Cyberattacks are accelerating rapidly, with attackers automatically probing vulnerabilities and intruding into systems within hours. Personal information leaks began with PARK24’s (4666) Times Car service, where data of about 6.6 million people was leaked, including images of driver’s licenses. This was followed by a series of data leaks affecting 10.78 million users of The Monogatari Corporation’s (3097) Yakiniku King app, 110,000 clients at Daiwa Securities Group (8601), and up to 1.73 million customers at Mr Max Holdings (8203). In addition, Osaka Metropolitan University was hit by a ransomware attack that took about 500 servers offline and forced the university to cancel all classes. As damage spreads across various sectors, implementing security measures has become an urgent priority for companies.
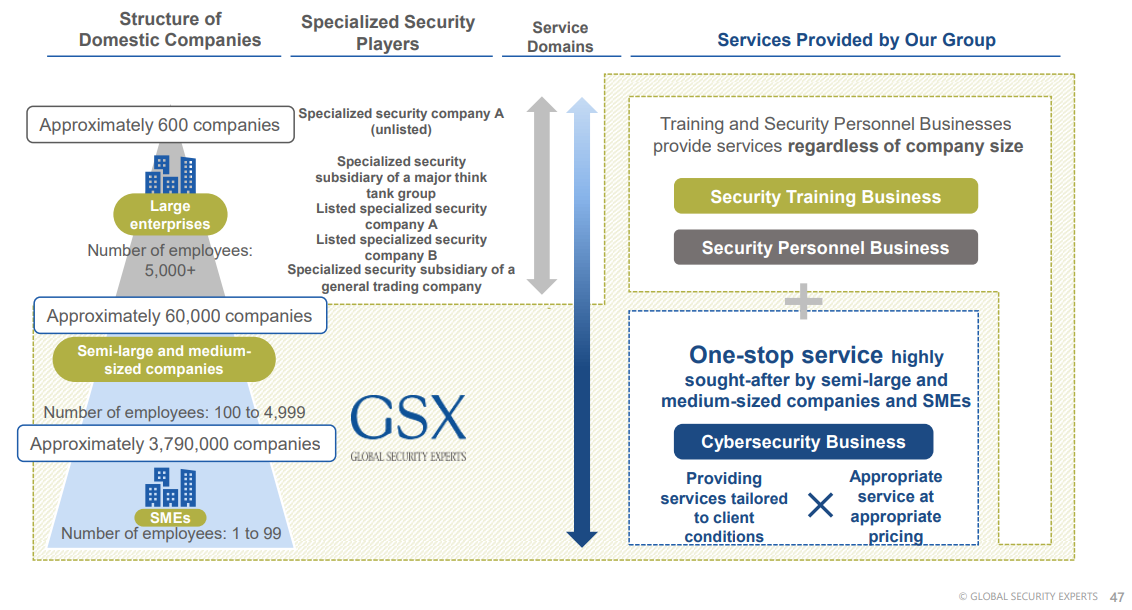
Global Security Experts can demonstrate an overwhelming strength in response to this surge in demand. This is backed by its distinct business model, which sets it apart from other cybersecurity companies. Many cybersecurity specialists have focused on large corporations as their customer base. They have emphasized providing high-priced, fully customized monitoring and tailored, extensive support structures. In contrast, Global Security Experts targets mid-tier, medium-sized, and small-to-medium enterprises, which often lag in adopting security measures. The company has established a unique positioning by offering services with appropriate pricing and content. These include Quick Assessment, which standardizes expertise into templates, and Managed Detection and Response, which is optimized for medium-sized companies. Its biggest differentiator is its security education and talent development business, which goes beyond merely selling and implementing IT products. Against the backdrop of a severe shortage of security personnel, the company offers training courses for international and in-house certifications to existing IT engineers at system integrators and IT companies. This business helps reskill these engineers into high-value-added security personnel.
Furthermore, the company has established a highly efficient operational structure that achieves both high growth and high profitability. The company delivers educational content online and on demand while accelerating and automating the creation of teaching materials through AI. It is also expanding its partner network with delivery partners and regional banks, primarily in regional cities. This system allows the company to rapidly expand its order capacity nationwide without increasing its fixed labor costs, thereby improving profit margins. Its effective cross-selling and upselling framework also functions well once the company establishes an initial foothold through consulting or assessment services. It diversifies its offerings to include vulnerability assessments, employee email training, security solution implementations, and talent provision. This expands its stable revenue base alongside gains in revenue per customer.
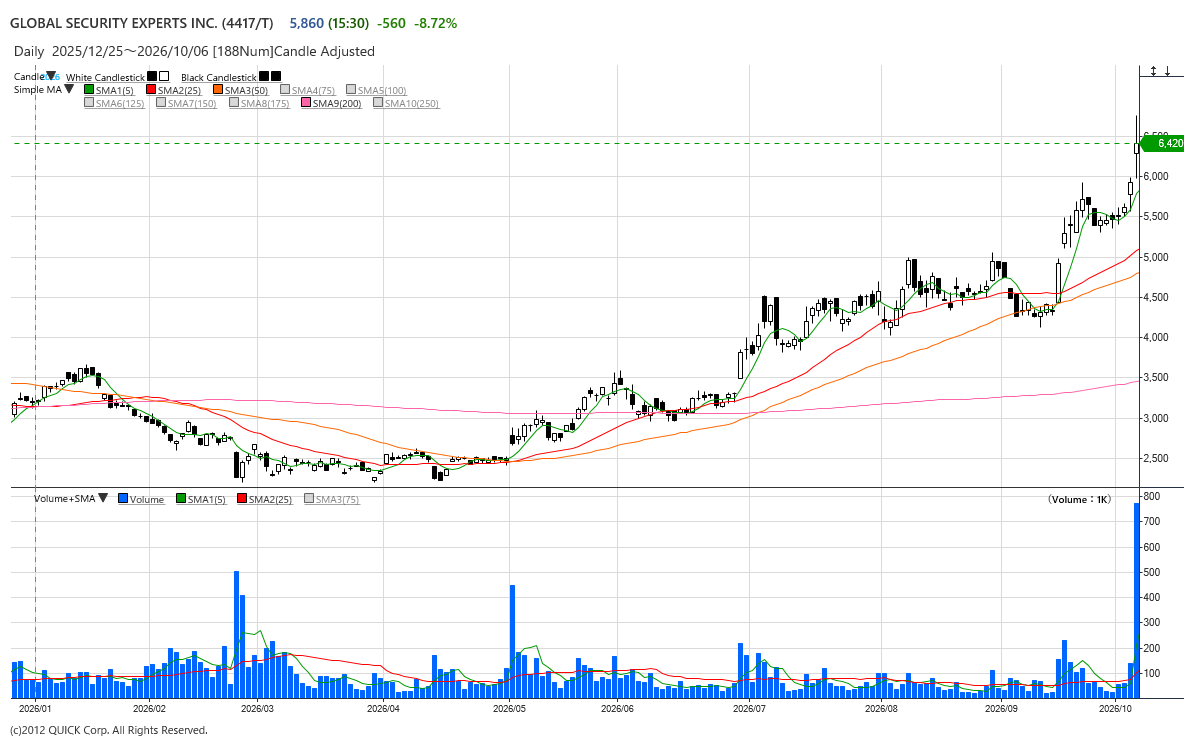
Recent business performance has been extremely strong. Consolidated financial results for the April-June 2026 period (Q1) showed a significant increase in both revenue and profit. Net sales rose 24% year on year to JPY2.7 bn, while operating profit jumped 42% to JPY499 mn. Driven by its core cybersecurity business, all segments – including security education and security talent services – expanded, setting new record profits for a Q1. The company maintained its full-year forecast as initially planned, targeting net sales of JPY13.7 bn (up 25%) and an operating profit of JPY2.9 bn (up 31%). However, the progress rate for Q1 operating profit reached 17%, exceeding the 16% recorded in the same period of the previous fiscal year. This performance raises expectations for upside earnings potential. Its proactive stance on shareholder returns is also noteworthy. The annual dividend is expected to increase significantly to JPY49.11 per share, up from JPY34.6 per share in the previous fiscal year. The stock had been trading around JPY3,000 since the beginning of the year. However, it has been gaining momentum since the summer, fueled by rising demand for cybersecurity services. The stock looks poised for a further rally.
(Reported on October 7, 2026)
Discover datasets unique to the Japanese equity market
Visit QUICK Data Factory: https://corporate.quick.co.jp/data-factory/en/
Disclaimer
https://corporate.quick.co.jp/en/terms/#disclaimer
Follow us on LinkedIn to stay updated with Japan Markets.