Japan Markets ViewELEMENTS (5246) Turns Profitable on Expanding eKYC Demand
Nov 04, 2026
[Akira Motoyoshi, QUICK Market Eyes] Generative artificial intelligence (AI) and malicious automation tools are on the rise. Along with this trend, problems such as phishing scams, account takeovers, fraudulent account openings using counterfeit documents, and illegal part-time job schemes have become increasingly severe in Japan. In this environment, market attention is rapidly growing toward ELEMENTS (Growth Market), a provider of online identity verification – electronic Know Your Customer (eKYC) – and biometric authentication solutions.
Regulatory tightening at the national policy level is accelerating. The Financial Services Agency (FSA) and the National Police Agency (NPA) have mandated the adoption of multi-factor authentication (MFA), including passkeys, in the securities and banking sectors. In addition, regulations such as the Act on Prevention of Transfer of Criminal Proceeds and the Mobile Phone Wrongful Use Prevention Act are being tightened. Under these circumstances, security infrastructure that balances spoofing prevention with user convenience has become an unavoidable, top-priority challenge for companies. Consequently, inquiries regarding the implementation of the company’s solutions are accelerating.
ELEMENTS has established overwhelming dominance amid this rapid market expansion. Behind this success are a proprietary business model centered on its general-purpose AI cloud platform “IoP Cloud” and strong barriers to entry. The company’s flagship service, “LIQUID eKYC,” boasts the top share in Japan’s domestic eKYC market. In 2025, ELEMENTS dramatically expanded its customer base by acquiring industry peer Polarify from Sumitomo Mitsui Financial Group. Currently, the company has secured a dominant market share. It covers 66% of banks that have implemented eKYC, and 96% of major mobile carriers on a subscriber basis. Unlike typical contract-based IT development vendors, the company securely stores acquired biometric data in-house and continuously trains its proprietary AI models on it. This establishes a “data flywheel” that drives strong network effects. As a result, authentication accuracy improves and abandonment rates decrease the more the service is used.
Furthermore, the company has established an extremely efficient operational structure that balances high growth with expanding contribution margins. During the post-merger integration of Polarify, ELEMENTS applied its advanced GPU management expertise. As a result, the company successfully reduced overlapping telecommunications expenses and cloud infrastructure costs by more than half. This completed an operating leverage structure where revenue growth significantly outpaces the increase in fixed costs. In addition, its cross-selling strategy is proving successful. It is expanding from “LIQUID eKYC” used for initial account openings to “LIQUID Auth” passkey authentication for daily logins and fund transfers. This strategy has strengthened a recurring-revenue base that extends beyond one-off verifications. Going forward, the company is also expanding into non-financial sectors. These include local governments, healthcare, crypto assets, the sharing economy, and markets outside Japan, thereby diversifying and layering its revenue opportunities.
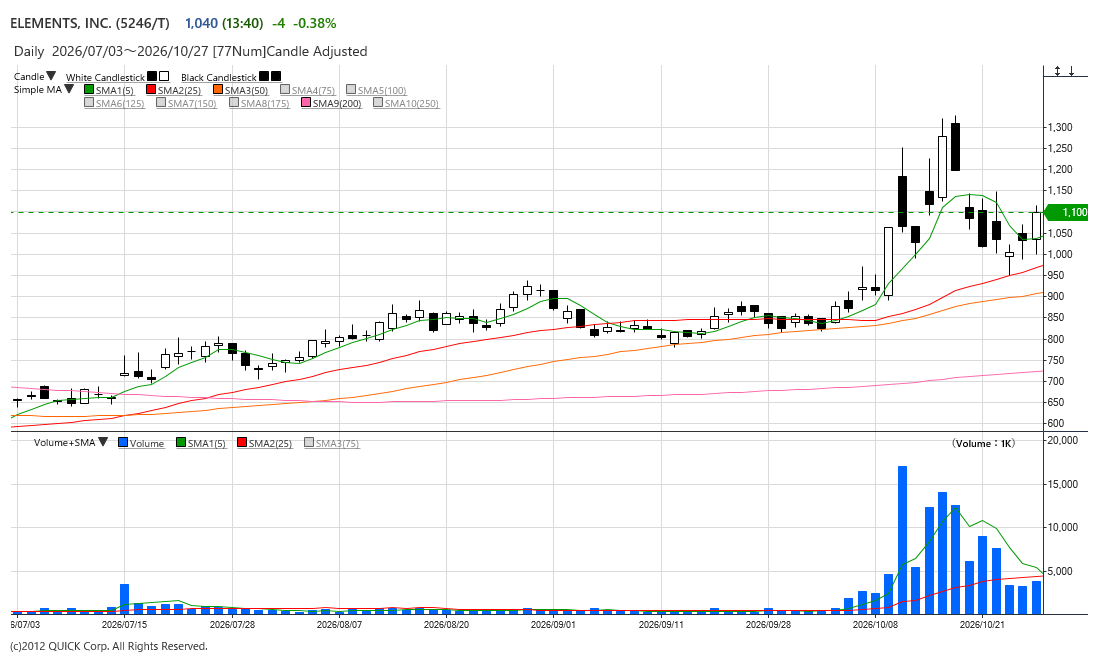
Recent business performance demonstrates a complete transition from an upfront investment to a profit realization phase. On October 14, ELEMENTS announced its consolidated financial results for the period from December 2025 to August 2026 (Q3 cumulative). Net sales increased 59% year on year to JPY4.3 bn. Operating profit reached JPY457 mn, turning profitable from an operating loss of JPY136 mn in the same period of the previous fiscal year. In addition to consolidating Polarify, strong performance in “LIQUID eKYC” drove substantial revenue growth and a return to profitability. In light of the solid recent results, the company raised its full-year earnings forecast for the fiscal year ending November 2026 to the upper end of its previous range. Net sales are projected to increase 46% year on year to JPY5.7 bn, and operating profit is projected to reach JPY400 mn, compared with the prior range forecast of JPY5.6 bn to JPY5.7 bn in net sales and JPY300 mn to JPY400 mn in operating profit. However, there still appears to be room for further upside. With the stock price consolidation phase having run its course, its shares are expected to test the year high of JPY1,330 recorded on October 19.
(Reported on October 28, 2026)
Discover datasets unique to the Japanese equity market
Visit QUICK Data Factory:https://corporate.quick.co.jp/data-factory/en/
Disclaimer
https://corporate.quick.co.jp/en/terms/#disclaimer
Follow us on LinkedIn to stay updated with Japan Markets.